VA Home Loans in Valrico FL: The Complete MacDill AFB Buyer's Guide for 2026
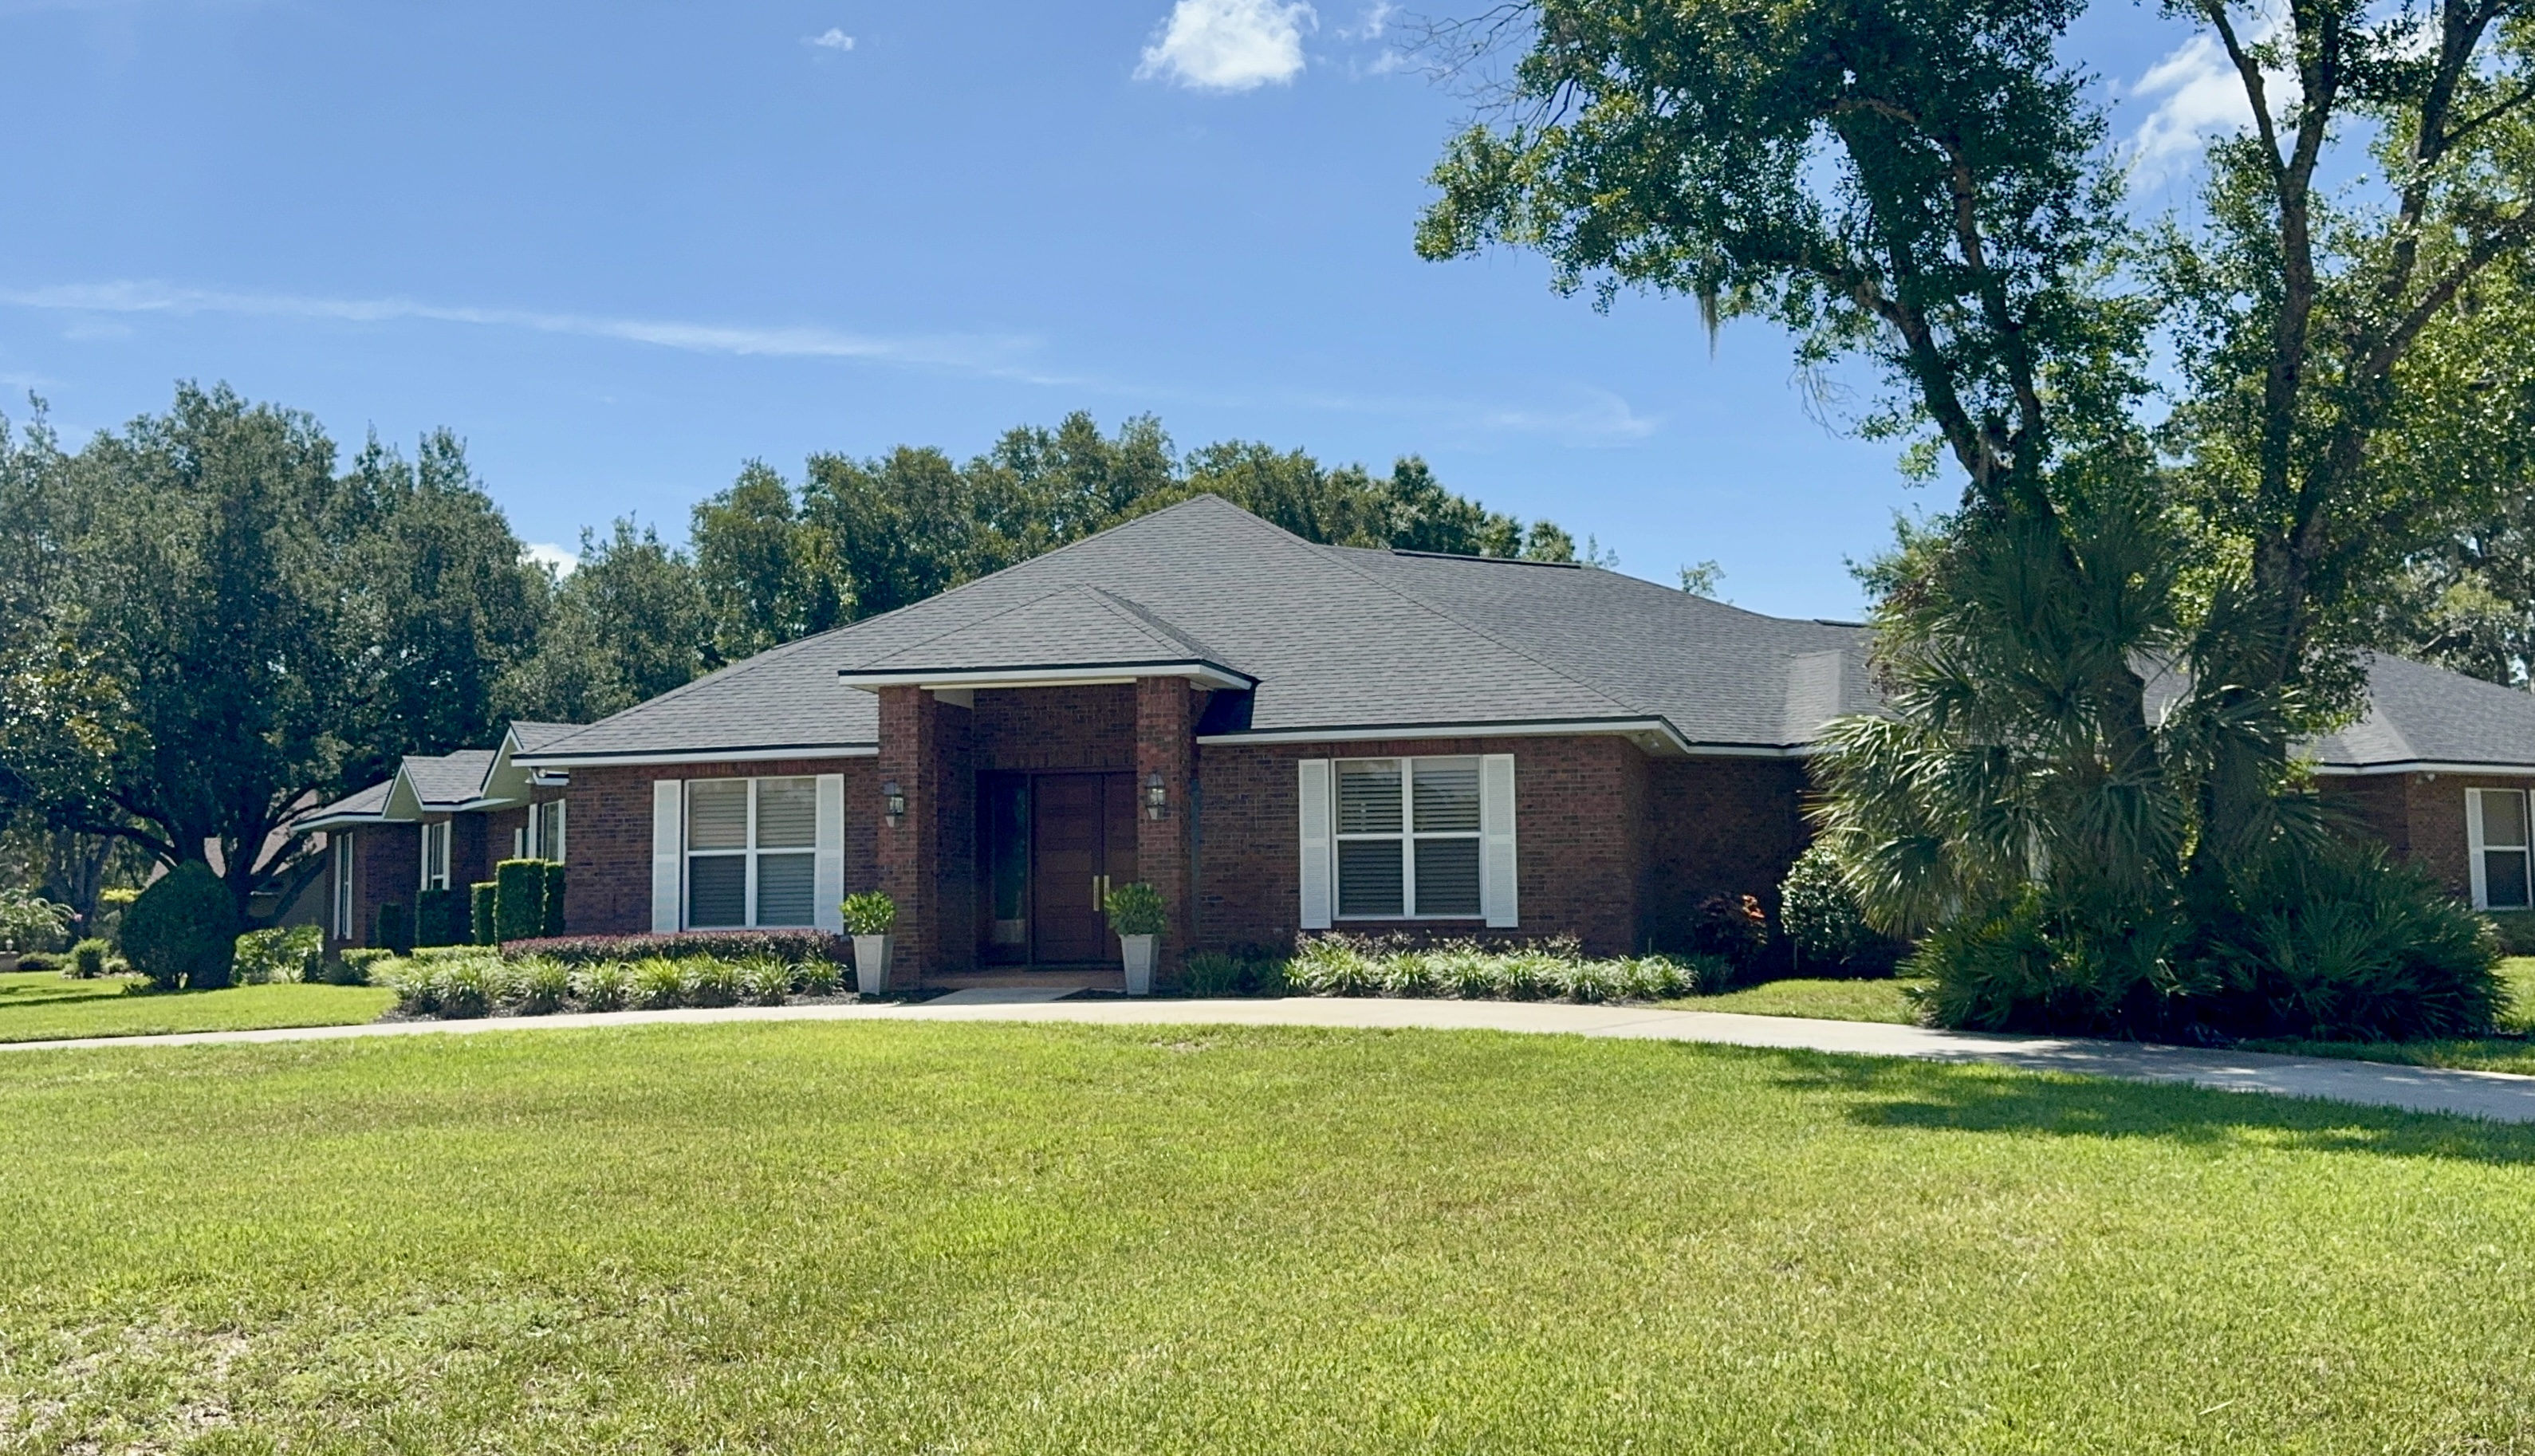
MacDill Air Force Base sits in South Tampa, approximately 25 to 35 minutes from most Valrico neighborhoods. For military personnel assigned to MacDill, Valrico offers a combination that is hard to find closer to the base: good schools, large lots, established neighborhoods, and home prices that make the VA loan benefit work with room to spare. Understanding how VA financing works specifically in the Valrico market in 2026 can mean the difference between overpaying on conventional financing and entering with maximum leverage and minimum cash out of pocket.
Why Valrico Works for VA Buyers
The VA loan program is most powerful in markets where home prices are moderate enough to stay within the zero-down ceiling. In Tampa proper and in some Wesley Chapel communities, prices have pushed toward and above $500,000 at the median, creating situations where VA buyers need partial down payments. Valrico's 33594 median of approximately $380,000 and 33596 median of approximately $470,000 both sit comfortably below the standard VA conforming limit of approximately $766,550 that applies to most Hillsborough County buyers with full entitlement.
In practical terms, this means VA-eligible buyers can purchase virtually any home on the current Valrico homes for sale market with zero down payment, no private mortgage insurance, and a competitive rate below the conventional market.
The VA benefit also aligns with what drives Valrico demand: stable employment and long holding periods. MacDill personnel who purchase in Valrico for a 2 to 4-year PCS assignment are taking a calculated risk on a short hold, but veterans who are separating or retiring near Tampa, or active duty personnel who plan to retain the home as a rental after relocation, are capturing long-term equity in a market with structural demand anchors.
The Full VA Loan Advantage at Valrico Price Points
No Private Mortgage Insurance
This is the most underappreciated VA benefit. On a $380,000 Valrico home financed conventionally with 5 percent down, PMI costs approximately $150 per month at current rates. PMI does not disappear until the loan-to-value ratio reaches 80 percent, which takes approximately 10 to 11 years at normal amortization on a 30-year loan at 6.75 percent. Over 10 years, that is $18,000 in PMI payments that VA borrowers never make.
The VA funding fee replaces PMI as the program's insurance mechanism, but it is paid once at closing or financed into the loan, rather than as an ongoing monthly charge.
Rates Below Conventional
According to Freddie Mac's Primary Mortgage Market Survey, the spread between VA and conventional 30-year fixed rates has averaged 25 to 50 basis points in 2026. At a 50-basis-point advantage, VA buyers accessing 6.25 percent versus conventional 6.75 percent on a $380,000 loan see a monthly payment difference of approximately $120. Over 30 years, that is $43,200 in interest savings.
The rate advantage exists because VA loans carry a government guarantee that reduces lender risk, allowing lenders to price VA loans more competitively than conventional products.
Zero Down Payment Preserves Cash
A VA borrower purchasing a $380,000 Valrico home with zero down keeps their entire cash position liquid. That cash earns investment returns, provides a maintenance reserve, or funds a future down payment on a second property. In contrast, a conventional buyer who puts $19,000 down has deployed that capital at a return equal to whatever their home appreciates -- which is competitive, but liquidity has value.
For MacDill personnel facing potential PCS orders in 3 to 5 years, keeping cash liquid provides optionality that a large down payment does not.
The VA Funding Fee: What You Actually Pay
The VA funding fee is a one-time cost that replaces ongoing PMI. Here is how it works for Valrico buyers in 2026.
First-time VA loan use, zero down payment: 2.15 percent of the loan amount.
On $380,000: $8,170 funding fee. Can be financed into the loan, bringing the total VA loan to $388,170.
Subsequent VA loan use, zero down payment: 3.3 percent.
On $380,000: $12,540 funding fee. Still financeable, still no down payment required.
Disability exemption: Veterans with a service-connected disability rating of 10 percent or higher pay no funding fee. This is a significant benefit for a large portion of the veteran buyer pool. If you receive VA disability compensation at any rating level, confirm with your lender whether your exemption applies before assuming you owe the fee.
Active duty Purple Heart recipients are also exempt from the funding fee.
For a first-time user purchasing at $380,000, the effective comparison looks like this:
| Loan Type | Down Payment | Monthly PMI | Rate | P&I Payment | Month 1 Cash Out |
|---|---|---|---|---|---|
| VA (0% down, fee financed) | $0 | $0 | 6.25% | $2,390 | $0-8,000 closing |
| Conventional (5% down) | $19,000 | $150 | 6.75% | $2,341 | $28,000-30,000 |
| Conventional (20% down) | $76,000 | $0 | 6.75% | $1,972 | $83,000+ |
The VA option at zero down produces a total monthly payment (including taxes and insurance but no PMI) of approximately $3,303 versus $3,444 for conventional with 5 percent down. VA wins on monthly payment even at zero down because the PMI elimination and rate advantage more than offset the slightly higher loan balance from the financed funding fee.
VA Minimum Property Requirements in Valrico
The VA loan program requires that financed properties meet Minimum Property Requirements (MPRs) that exceed what conventional or FHA financing requires. These standards exist to protect the buyer as much as to protect the loan, but they can create friction on older homes or properties with deferred maintenance.
Common MPR Issues in the Valrico Market
Roof condition: The VA requires the roof to have a remaining useful life of at least two years. A roof inspector's estimate of "2 to 3 years of remaining life" will likely require a replacement as a condition of VA financing. Bloomingdale and Copper Ridge have large numbers of homes built in the early 2000s with original roofs approaching or past the 25-year mark. VA buyers should budget for a roof credit request or be prepared for the seller to carry the cost.
Electrical and plumbing: Active electrical hazards (exposed wiring, inoperative GFCIs in wet areas, panel issues) and plumbing deficiencies (active leaks, galvanized supply lines in certain conditions) can flag in VA appraisals. These issues are common findings in pre-2000 construction in the 33594 market.
Pool enclosures: The VA does not automatically flag a pool, but a damaged or torn pool screen enclosure may be noted if it presents a safety concern. Pool equipment in non-functional condition is similarly noted.
Foundation and structural: Any visible cracking with suspected active movement, or evidence of water intrusion affecting structural elements, will typically require engineering documentation before VA financing proceeds.
Navigating MPR Risk in Valrico
MPR issues are manageable in a buyer's market where sellers are negotiating. A seller who has been on market for 45-plus days in 33594 is more likely to address a roof credit request than a seller who received five offers in the first week. The current Valrico market conditions with 30 to 32 percent of active listings carrying price reductions make VA-condition negotiations more feasible than they were in 2022.
Buyers can further reduce MPR risk by focusing on homes built after 2005 in Buckhorn Preserve, Copper Ridge, or Twin Lakes where roofs are more likely to have useful life remaining, and by requesting a pre-offer seller's disclosure that identifies any known deficiencies.
Entitlement, COE, and the Pre-Approval Process
VA buyers need two key documents before making offers: a Certificate of Eligibility (COE) and a lender pre-approval letter.
The COE confirms your entitlement to VA financing and can be obtained through the VA's eBenefits portal or directly through a VA-approved lender. Most VA lenders can pull the COE electronically in minutes as part of the pre-approval process.
Entitlement works in two tiers. Basic entitlement ($36,000) covers loans up to $144,000. Bonus or second-tier entitlement covers loans above $144,000 up to the conforming limit, which is approximately $766,550 in Hillsborough County. For most Valrico purchases, buyers use both tiers and have full zero-down entitlement available.
Buyers with a prior VA loan that is paid off have their entitlement restored and can use VA financing again at zero down. Buyers who have a current VA loan that has not been paid off can still use remaining entitlement if enough is available for the new purchase, though this typically requires a partial down payment calculation.
For military buyers looking to use a VA loan while transitioning from a current VA-financed property, discuss the entitlement status with a VA-specialized lender before beginning your search. Barrett Henry works with VA-experienced lenders in the Tampa Bay area who understand these scenarios.
The Valrico Market for VA Buyers in Fall 2026
The buyer's market conditions entering fall 2026 work particularly well for VA buyers. Here is why.
Seller concessions cover closing costs. In a market where sellers are routinely offering 1 to 3 percent closing cost credits, VA buyers can often enter with truly minimal cash out of pocket. The VA allows sellers to contribute up to 4 percent toward buyer costs on VA transactions (higher than the conventional 3 percent limit for some loan types). This means a seller can cover the funding fee, prepaids, and all closing costs in a motivated-seller negotiation -- reducing the effective cash-to-close to near zero.
Price reductions create VA appraisal alignment. VA appraisals are sometimes criticized as conservative because they are meant to reflect market value, not speculative premiums. In a market with 30 percent of listings having already taken price reductions, the gap between list price and appraised value has narrowed substantially compared to the 2021 to 2022 peak. VA buyers in fall 2026 are less likely to encounter the "appraisal gap" situation where the VA appraiser comes in below the negotiated contract price.
Extended days on market create negotiating room. With median days on market at 50 to 60 days in 33594 and 35 to 50 days in 33596, sellers have typically done extensive market education by the time a VA offer arrives. They know their home has been available for 6 to 8 weeks. They know competing buyers have options. VA offers with strong pre-approval letters and competitive prices are evaluated on merit, not on financing type.
The Newsome zone in 33596 has demand from military families. The 33596 ZIP and its Newsome High School zone has meaningful demand from MacDill-assigned families who want their children in a top-rated public high school and are willing to pay for it. This creates a buyer pool that is VA-eligible in significant numbers, and sellers in that zone are familiar with VA financing as a result.
Working With a VA-Experienced Agent in Valrico
Not all real estate agents have meaningful VA transaction experience. The nuances of VA appraisals, VA addenda language, the VA escape clause, seller contribution rules, and MPR mitigation strategy require experience to navigate correctly.
Barrett Henry, Broker Associate at REMAX Collective, has worked with VA buyers in Valrico and east Hillsborough County for over 23 years including clients from MacDill's operational, support, and contractor community. Barrett knows which Valrico neighborhoods present lower VA appraisal risk, how to structure offers that address seller concern about VA timelines, and how to use the current buyer's market conditions to achieve the strong negotiating position VA buyers deserve.
To start your VA home loan search in Valrico or ask specific questions about how VA financing works for your situation, contact Barrett at (813) 733-7907 or browse current Valrico listings to see what zero-down VA financing gets you today.
---
Sources: U.S. Department of Veterans Affairs VA Home Loan Program, Freddie Mac Primary Mortgage Market Survey 2026, Zillow Valrico FL Home Values 2026, Redfin Hillsborough County Housing Market, Florida Realtors Market Statistics Q3 2026.
Looking for Homes in Valrico?
Get daily listings that match your must-haves. No spam, no portal runaround.
Get Custom Valrico ListingsFrequently Asked Questions
Can I use a VA loan to buy a home in Valrico FL?
Yes. VA loans are available in Valrico FL with no county-level restrictions. Both 33594 and 33596 ZIP codes are well within the standard VA conforming loan limit, which covers purchases through approximately $766,550 with full entitlement and no down payment. Higher-value homes are also eligible with a partial down payment on the amount above the limit. Valrico's typical price range of $340,000 to $550,000 falls comfortably within zero-down VA eligibility for buyers with full entitlement.
What is the VA loan funding fee for a Valrico FL home purchase in 2026?
The VA funding fee for a first-time VA loan use with zero down payment is 2.15 percent of the loan amount. On a $380,000 Valrico home, that is $8,170 which can be financed into the loan rather than paid at closing. For subsequent VA loan use, the fee rises to 3.3 percent. Veterans with a service-connected disability rating of 10 percent or higher are exempt from the funding fee entirely. Active duty Purple Heart recipients are also exempt. The funding fee replaces the PMI cost that conventional borrowers pay, and since it can be financed, it does not require upfront cash.
How does a VA loan compare to a conventional loan for buying in Valrico FL?
At fall 2026 rates, VA loans are running approximately 6.25 to 6.5 percent on 30-year fixed loans for buyers with strong credit, compared to 6.75 percent for conventional conforming loans. On a $380,000 purchase, VA with zero down has a principal and interest payment of approximately $2,342 per month (financing the funding fee at 2.15%), while conventional with 5 percent down at 6.75 percent runs $2,341 plus $150 per month in PMI. VA eliminates PMI entirely, making the total payment actually lower than conventional with 5 percent down even though the VA loan amount is higher. VA buyers also preserve their $19,000 down payment as a cash reserve.
Are sellers in Valrico FL willing to accept VA loan offers in 2026?
Yes. In the current buyer's market with 110 to 130 active listings in 33594 and 40 to 55 in 33596, sellers do not have the leverage to reject VA offers as some did during the 2021 to 2022 peak. VA appraisals are sometimes conservative and VA minimum property requirements can flag deferred maintenance, but an experienced VA buyer's agent can identify properties that will clear VA underwriting, select an appraiser-friendly offer strategy, and address any property condition issues in negotiation. Barrett Henry has worked VA transactions in Valrico for over 20 years and knows which communities and property types present VA appraisal risk.
Keep Reading
Valrico FL Buyer's Market Fall 2026: Price Reductions, More Inventory, and How to Negotiate
8 min readMarket ReportValrico FL Housing Market October 2026: Inventory, Rates, and What Buyers and Sellers Should Know
8 min readBuyer GuideRent vs. Buy in Valrico FL: The Complete Cost Breakdown for Fall 2026
8 min read
Barrett Henry, REALTOR® & Broker Associate
23+ years of real estate experience. Designations: e-PRO, MRP, SRS. Serving Valrico's 33594 and 33596 zip codes through REMAX Collective.
(813) 733-7907Information is deemed reliable but not guaranteed. Content is for informational purposes only and is not intended as legal, financial, or tax advice. Consult a licensed professional for advice specific to your situation.